Written by Corey L. Stokes
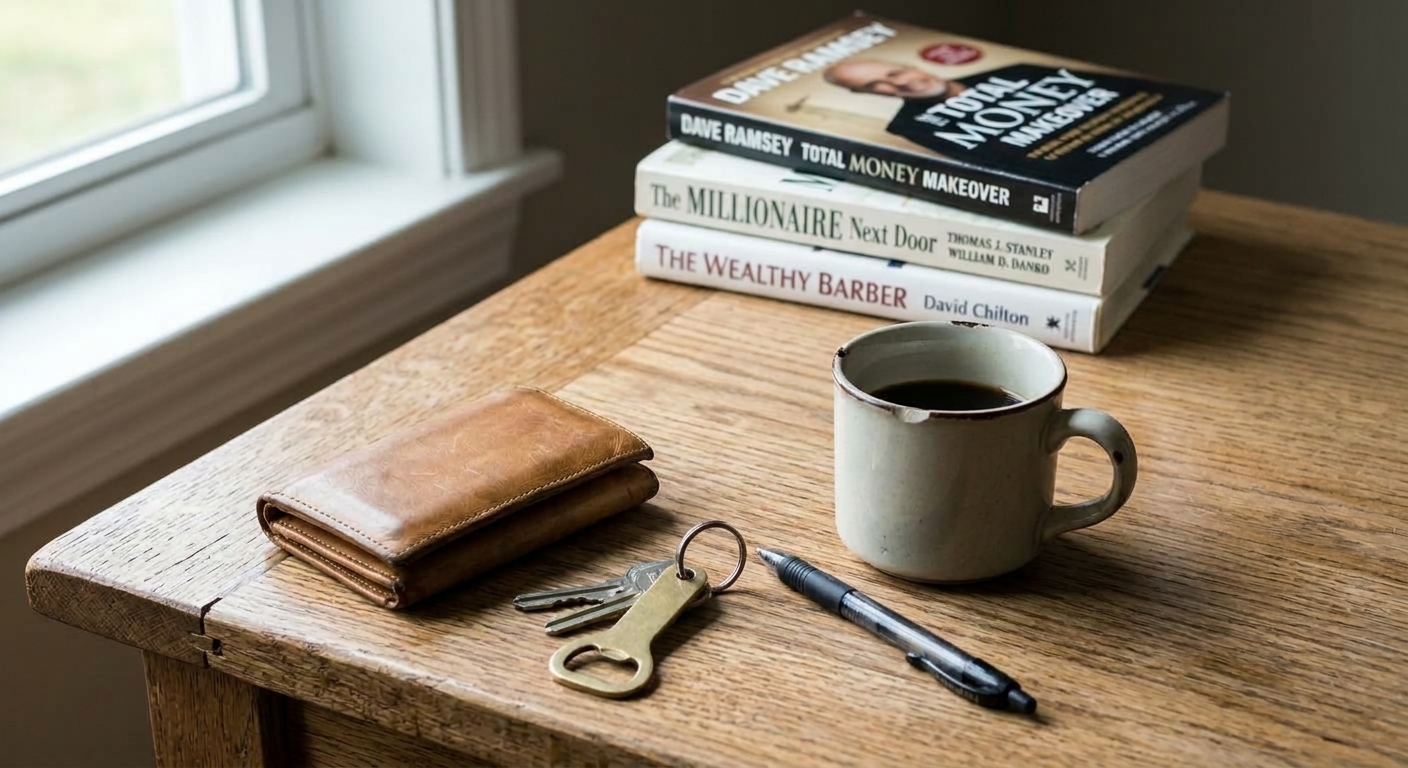
Alright, let’s talk about building wealth. For a moment, let’s just be real about it. If you have spent any time reading the personal finance section of books, but specifically books like The Total Money Makeover, The Millionaire Next Door, and The Wealthy Barber, you start to notice something interesting. These books are written decades apart by completely different types of authors, but at their core, they are all screaming the exact same message. People just love to complicate it because simple truths are boring and buying stuff is fun.
Let us start with Dave Ramsey and The Total Money Makeover. Ramsey is loud, he is intense, and he treats debt like a house fire because, frankly, when you are in debt, it is. When you read his stuff, the big takeaway is that debt is an anchor chained to your ankle as you try to swim across a pool. Most people think they have an income problem when they actually have a lifestyle and debt problem. You can make two hundred thousand dollars a year and still be flat broke if your truck note, your boat payment, your timeshare, and your minimum credit card balances swallow every single dollar before it even hits your bank account. Ramsey forces you to look in the mirror and admit that behavior is the real enemy. You have to get mad at debt. You have to stop borrowing money for depreciating junk just to impress people you do not even like. Until you clear the decks and gain control of your monthly cash flow, you are just running on a treadmill, and no investment strategy will save you.
Then you pivot over to Thomas Stanley and The Millionaire Next Door, and this is where your entire mental picture of what a wealthy person looks like gets completely shattered. Hollywood and social media want us to believe that millionaires are driving Lamborghinis, wearing designer suits, and dropping thousands of dollars at trendy rooftop bars (and believe me, they are just like any other bar) every weekend. But Stanley spent years actually studying real millionaires, and guess what he found? Most of them are driving a three-year-old Ford F-150, living in a normal neighborhood they bought decades ago, wearing clothes from JCPenney, and mowing their own lawns. They are frugal to the core. They understand the difference between income and wealth. Income is what you make, and wealth is what you keep and accumulate. If you make two hundred grand and spend two hundred and ten grand, you’re still broke. The typical millionaire next door is someone who lives well below their means, saves aggressively, avoids lifestyle creep, and treats building net worth as a slow, steady discipline rather than a flashy performance. In my opinion, the faster you make it, the quicker you can lose it, because you don’t appreciate what you’ve built.
And then you round it out with David Chilton and The Wealthy Barber. Chilton takes this entire concept and wraps it in a brilliant, conversational story that introduces probably the most famous and practical rule in personal finance: pay yourself first. Most people make the mistake of getting paid, paying all their bills, going out to eat, buying clothes, living life, and then hoping and praying there is something left over at the end of the month to save. Spoiler alert: there never is. The money just disappears. Chilton flips the script completely. The very first check you write out of every paycheck needs to go to your future self. Take ten to fifteen percent right off the top and invest it before you even see it in your checking account. If you never see it, you never spend it. You adapt your lifestyle to what is left over. It sounds painful at first, but your brain is amazing at adapting. You figure out how to live on eighty-five percent of your income without feeling like you are suffering. Combined with the magic of compound interest over a long horizon, paying yourself first turns ordinary, middle-class workers into wealthy retirees without requiring them to pick winning stocks or time the market.
When you mash these three books together into one practical philosophy, you realize that building wealth is actually pretty boring. There is no secret hack. There is no magical crypto coin or get-rich-quick real estate seminar that replaces the boring fundamentals. When you realize this, it changes your total outlook on building wealth.
It starts with behavior. You have to stop spending money you do not have to buy things you do not need to impress people who do not care. That is Ramsey talking. You have to clean up the messes of the past, attack your consumer debt with a vengeance, and build a solid emergency fund so that one flat tire or broken water heater does not send you running back to the plastic or disrupt your world.
Once the foundation is clear, you shift into the mindset of the millionaire next door. You stop playing the comparison game. Who cares what your neighbor drives? Let them have the flashy car payment (and the payment to boot), and the stress of a suffocating mortgage. You want financial peace. You want options. You want the freedom to walk away from a bad job or take a risk on a new venture because your bank account gives you breathing room. Being frugal is not about being cheap or miserable. It is about prioritizing what actually matters to you rather than wasting your money on superficial garbage that loses its novelty within three days.
And finally, you automate the process just like the wealthy barber taught us. Set up automatic transfers every single payday. Send money straight to your retirement accounts, your brokerage accounts, and your savings buckets. Make wealth building your default setting. When saving is automated, you take human emotion and willpower completely out of the equation. You do not have to wake up every month and decide whether you feel like saving money. The system just handles it in the background while you go live your life, work your job, spend time with your family, and focus on the things that bring genuine fulfillment.
The funny thing about wealth is that people talk about it as if it were some distant mountain peak that only a chosen few can climb. But the authors of these three books are all telling us the same thing. The mountain is not that high, and the trail is clearly marked. The only reason most people never make it to the top is that they keep stopping to pick up heavy rocks along the way, loading themselves down with debt, trying to look rich for an audience, and refusing to adopt the simple, unsexy habits that actually move the needle. Put down the flashy rocks, get and stay out of debt, stop complicating your financial story.
So where does that leave you? It leaves you with a choice. You can keep playing the game on hard mode, constantly chasing the next pay raise only to watch your expenses expand right alongside it, stressing over bills, and wondering where all the years went. Or you can decide to simplify. Clean up your debt. Live below your means so your money can actually go to work for you. Pay yourself first every single time money hits your hands.
It takes time. It takes discipline. It takes ignoring the noise of a culture that tells you your worth is measured by what you consume. But if you stick to the basics, stay consistent, and let time and compound interest do their quiet, heavy lifting, you will wake up one day and realize you have built something solid. You do not need to be a Wall Street genius. You just need to be intentional, stay the course, and let the boring math work its magic in your favor.

